
Florida’s Condo Insurance Market Is Finally Loosening Up — Here’s What Actually Changed
In This Story
- Twenty new property insurers have entered Florida since 2023’s litigation reforms, bringing in more than $850 million in new capital — three of them just this spring
- Citizens Property Insurance is recommending its first rate cut since 2015, with three in five policyholders in line for an average $359 reduction
- Why coastal high-rises with older roofs are still getting hard-market quotes even as pricing eases elsewhere
A Market That’s Actually Loosening
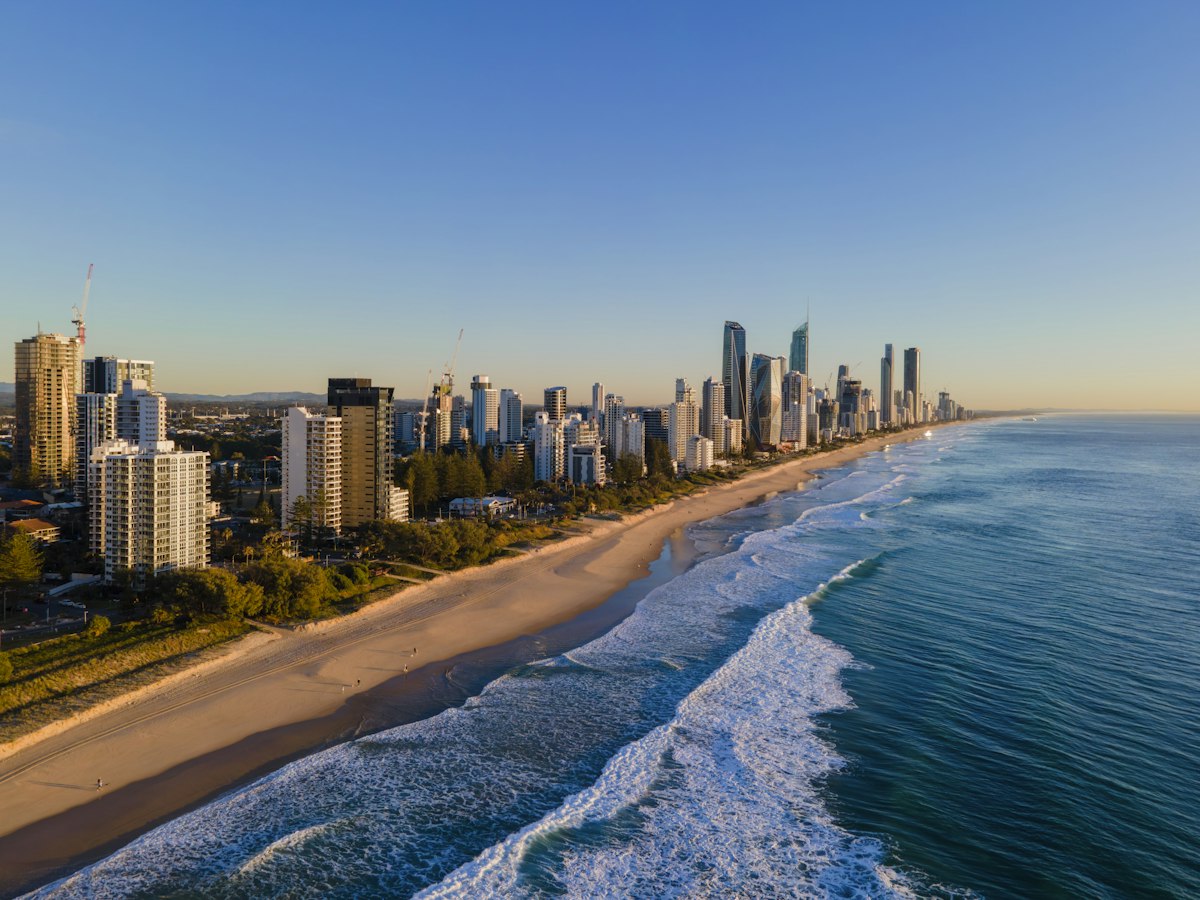
Florida’s Insurance Commissioner announced in May that 20 new property and casualty insurers have entered the state since the 2023 litigation reforms took effect — three of them in spring 2026 alone, bringing more than $850 million in fresh capital into the market. The number of carriers writing condo association wind-only policies in Miami-Dade, Broward, and Palm Beach counties has grown from one to five, and a new entrant, Condo Owners Reciprocal Exchange, is writing HO-6 condo-unit policies specifically. Insurance Journal reported the shift as the clearest sign yet that the market is stabilizing, not just slowing its decline.
Florida’s 2023 reforms ended assignment-of-benefits abuse and one-way attorney fees — the two mechanisms insurers blamed for years of runaway litigation costs. Statewide insurance litigation is down nearly 50% in the 18 months since, and Florida domestic insurers’ combined ratio, a core measure of underwriting profitability, improved from 94% to 83% year over year. Insurers that were pulling out of the state three years ago are now competing for business again.
Citizens Is Cutting Rates for the First Time Since 2015
Citizens Property Insurance’s Board of Governors approved 2026 rate recommendations calling for a statewide average 2.6% decrease on personal lines policies, with three of five policyholders in line for an average reduction of 11.5%, or about $359 a year, pending final approval from state regulators. Citizens’ own announcement credits the same litigation reforms for taking pressure off the state’s insurer of last resort — the same wave of new entrants competing for business Citizens used to absorb by default.
For associations, a shrinking Citizens book matters less directly than what it signals: real competition returning to the private market for the first time in years.
Not sure if your current policy reflects the improving market?
A free policy review can show whether your association is still paying 2023-era hard-market pricing on a 2026 market — and where you might be leaving savings on the table.
The Catch — Coastal High-Rises Aren’t Feeling It Yet
None of this means every renewal is getting easier. Florida condo premiums still average around $8,458 a year — roughly three times the national average — and coastal buildings in Miami-Dade and Monroe counties are seeing policies priced at $11,000 or more, compared to roughly $5,500 for inland communities. Miami-Dade high-rise HOA fees jumped nearly $500 a month in 2025, with insurance alone accounting for about $377 of that increase.
The new capital entering the market is being underwritten carefully. Carriers are competing hardest for buildings with recent roofs and completed milestone inspections — not for older coastal towers still working through SIRS-driven repairs. Condo sales were up 7% year over year as of this spring, but agents and lenders both report that insurance cost, more than price, is now the more common reason a sale falls through.
What This Means for Your Association’s Next Renewal
The broader easing is real, but it won’t show up in your renewal automatically. Boards should be getting quotes from more than one carrier this cycle — with five wind-only writers now active in South Florida versus one a few years ago, there’s more to compare than there used to be. Buildings that have completed milestone inspections and can document a funded reserve study are best positioned to capture the new competition; buildings still carrying deferred maintenance are the ones still facing hard-market pricing, regardless of what’s happening statewide.
Frequently Asked Questions
Does this mean our premiums will go down automatically?
Not automatically. The rate relief is showing up most for personal-lines Citizens policyholders and for newer, well-maintained buildings competing among the new private carriers. Associations still carrying deferred maintenance or an incomplete milestone inspection generally aren’t seeing the same relief yet.
What makes coastal high-rises different from the rest of the market?
Coastal exposure, building age, and roof condition are the biggest underwriting factors carriers weigh, regardless of the statewide trend. A high-rise with an aging roof and no completed milestone inspection is priced on its own risk profile, not the market average.
Should our board shop the market again before the next renewal?
Yes. With wind-only carriers in South Florida up from one to five in a few years, and 20 new entrants writing statewide, there are more carriers to quote against than there were even a year ago — worth confirming even if your building doesn’t end up qualifying for relief.
Is Citizens still worth considering if we can’t find private coverage?
Citizens remains available as the insurer of last resort, but its 2026 rate recommendation is a decrease, not an expansion of eligibility — private-market alternatives still get evaluated first under Citizens’ own rules.
You Might Also Like
Is Your Community Protected?
Get a free policy review and find out if your association is overpaying for insurance.
Get My Free Policy Review →
Have a question about this story or your own community’s coverage? Contact Daniel directly →